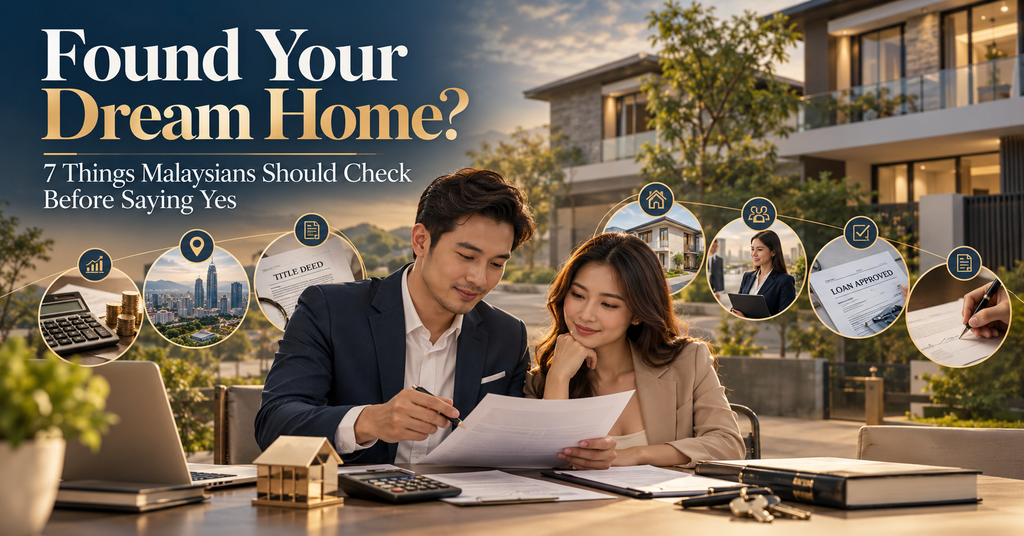
Buying a property is probably one of the biggest financial commitments most Malaysians will make in their lifetime.
It is therefore understandable that when we finally find a house that looks right, is located in our preferred area and seems to be within our budget, we may be tempted to quickly say, “This is the one.”
However, a property should not be chosen based on appearance or price alone.
Before paying a booking fee, signing an Offer to Purchase (“OTP”) or committing yourself to a Sale and Purchase Agreement (“SPA”), there are several practical matters which every property buyer should consider carefully.
1. Can You Really Afford It?
The first question should not simply be, “How much can the bank lend me?” A more important question is whether you can comfortably afford the monthly commitment after taking into account your existing expenses and other financial obligations.
The purchase price is only one part of the overall cost of owning a property. Apart from the deposit and monthly housing loan instalments, a buyer should also take into account legal fees, stamp duties, valuation fees, loan-related expenses, renovation and furnishing costs, maintenance charges, sinking fund contributions, quit rent, assessment and future repair costs.
For example, buying a RM500,000 property does not mean that your financial commitment ends at RM500,000. There will usually be additional expenses before and after completion of the purchase.
If you would like to know the estimated legal fees and disbursements involved, you may contact us for a
free calculation of the legal costs and disbursements:
It is therefore important to calculate carefully and leave yourself some financial breathing space. A house should improve your quality of life, not cause unnecessary financial stress every month.
2. Location Is Important, But Look Beyond the Address
We often hear the phrase, “Location, location, location.” There is certainly some truth in it, but a good location means different things to different buyers.
For someone buying a property for his or her own stay, matters such as the distance to the workplace, availability of schools, hospitals, supermarkets, public transportation, road accessibility and the general safety of the surrounding area may be equally important.
It may also be useful to visit the area at different times of the day. A neighbourhood may appear quiet and convenient on a Sunday afternoon, but the actual situation may be very different during weekday peak hours.
Buyers should also try to understand the surrounding development plan and what may be built in the area in the future. For example, is there any proposed shopping mall, school, place of worship, commercial development, high-rise building or major road nearby? A vacant piece of land beside the property today may not remain vacant forever. Future developments may improve convenience and property value, but they may also bring heavier traffic, noise, congestion or other practical concerns.
This is also one reason why buying a “new house” directly from a developer may not always be the better choice from a practical point of view. In a newly developed area, the buyer may be purchasing based largely on brochures, plans and what the neighbourhood is expected to become. In contrast, when buying a subsale property in an established area, the buyer can usually see the actual surroundings, existing traffic conditions, nearby amenities and the general living environment before making a decision.
Similarly, a journey which appears to take only 15 minutes on a map may become a much longer daily commute during rush hour.
For this reason, buyers should not merely look at the property itself. The surrounding neighbourhood, existing conditions and future development of the area may be just as important as the house itself.
3. Understand What You Are Actually Buying
A common mistake among first-time buyers is to assume that all properties are legally the same. They are not.
Before purchasing, a buyer should understand the type of property being purchased and the nature of its title. For example, there may be important differences between conventional landed properties, strata properties and the increasingly common landed strata developments. Buyers should also understand whether the property is freehold or leasehold, whether an individual or strata title has been issued, or whether the property is still held under a master title.
There may also be properties subject to restrictions in interest, Bumiputera conditions, “Tanah Yang Dikurniakan”, or requirements for consent from the relevant authority before the transfer can be completed.
For strata properties, such as condominiums and apartments, buyers should understand matters such as maintenance charges, sinking fund contributions and the management arrangements of the development. However, buyers should also be aware that nowadays even landed houses may form part of a strata development.
At the same time, a conventional landed property which is not a strata property may still form part of a gated and guarded community, subject to its own arrangements, charges or community rules.
For this reason, buyers should always check the actual legal and practical arrangement of the property rather than relying merely on how it is marketed or described by the property agent or developer.
These matters may affect the legal procedures involved, the time required to complete the transaction, the buyer’s financing, future expenses and even the ability to sell, transfer or deal with the property later.
Therefore, if you do not understand the title or any document shown to you, do not be shy to ask questions. It is always better to clarify the position before making what may be one of the biggest financial commitments of your lifetime.
If you would like us to help you understand the title or the legal position of a property before you proceed, you may contact us at:
4. New Launch or Subsale Property?
Buying a newly launched property and buying a subsale property involve different considerations.
For a new development, buyers are often attracted by the showroom, promotional materials, facilities and incentives offered by the developer. However, buyers should remember that they are purchasing the actual property to be delivered in the future, and not the showroom itself.
It is therefore advisable to look at the developer’s previous projects, delivery record, workmanship and overall reputation before making a decision.
For a subsale property, the buyer has the advantage of being able to physically inspect the property before committing to the purchase. The condition of the property, possible water leakage, cracks, renovation works, electrical systems, plumbing, outstanding maintenance charges, as well as the fixtures and fittings included in the sale, should all be carefully considered.
If certain items or conditions are important to the buyer, they should not be left as mere verbal promises. Where appropriate, they should be recorded in writing as early as possible, preferably in the Offer to Purchase (“OTP”).
What is an OTP? You may read our article here:
What is an Option to Purchase?
For property investors, there is another option to consider: purchasing a property through lelong, or public auction.
Yes, we agree — if you manage to buy the right property at the right price, it may turn out to be a very successful investment, perhaps even one worth talking about for the next ten years.
But… what if there is still an occupier residing in the property after you have successfully purchased it, settled the balance purchase price and, technically, obtained legal possession of the property?
This is where matters may become more complicated. Depending on the circumstances, the purchaser may first need to identify who is occupying the property and whether that person has any lawful right to remain there. In many cases, the occupier may have no legal right to continue occupying the property.
If the occupier refuses to vacate, simply issuing a formal eviction notice may not be sufficient. The purchaser may have to take the appropriate legal steps to recover vacant possession, which may include commencing court proceedings where necessary.
For this reason, buyers should not assume that purchasing a property at auction automatically means they will be able to obtain vacant possession immediately.
If you are facing this problem or are interested in this topic, kindly contact us. We may also write a separate article in the future to discuss the legal and practical issues relating to occupied auction properties in more detail.
5. Check Who You Are Dealing With
Many buyers first come across a property through Facebook, online advertisements, WhatsApp or property agents. There is nothing unusual about this, but buyers should still know who they are dealing with before making any payment.
Where a person represents himself or herself as a property agent or negotiator, it is prudent to verify the person’s registration particulars.
For a new development, buyers should also make sure that the person marketing the project is genuinely authorised to do so.
Particular care should be taken when a buyer is asked to transfer a booking fee or deposit into an individual’s personal bank account. Before making any payment, the buyer should be clear about who is receiving the money, in what capacity the money is being received and what will happen to the payment if the transaction does not proceed.
A simple verification at the beginning may prevent a much larger problem later.
6. Do Not Assume Your Housing Loan Will Be Approved
A buyer may feel that he or she earns enough to pay the monthly instalment, but that does not necessarily mean that a bank will approve the housing loan.
Banks may take into account income, existing car loans, personal loans, credit card commitments, PTPTN, credit records, employment status and overall financial commitments when considering a loan application.
For this reason, it may be sensible to speak to a banker early and understand your borrowing position before committing yourself to a purchase.
More importantly, if the purchase depends on obtaining a housing loan, the buyer should check whether the OTP or booking document provides any protection in the event the loan application is rejected.
A buyer should not simply assume that a rejected loan automatically entitles him or her to a refund of the deposit. Whether the deposit is refundable will depend on the terms agreed between the parties.
7. Read Before You Sign!!!
This is perhaps one of the most important matters from a legal perspective.
Many buyers assume that the transaction only becomes serious when the SPA is signed. However, before the SPA is prepared, a buyer may already have signed an Offer to Purchase, Letter of Offer, Booking Form, Earnest Deposit Form or other similar document.
Whatever the document may be called, its contents should be read carefully before signing.
The buyer should understand the agreed purchase price, the amount of deposit paid, whether the deposit is refundable, the deadline for signing the SPA, whether the purchase is subject to loan approval, what happens if either party refuses to proceed and whether any fixtures, fittings or special conditions have been agreed.
Do not sign first and ask questions later.
By the time a dispute arises, the question may no longer be whether you still want to buy the property, but whether you are already legally bound to proceed with the purchase.
Please read our separate article – “What is an Option to Purchase?” to learn more.
Conclusion: Buy With Your Head, Not Just Your Heart
Finding a home that you love is important, but a property transaction involves much more than finding a nice house in a good location.
Before committing yourself, take some time to understand your financial position, investigate the property, check the people you are dealing with and, most importantly, understand the documents you are signing.
A little homework before the purchase may save you from considerable financial and legal problems afterwards.
When in doubt, it is usually better to speak to your banker, registered property professional or lawyer before signing the documents, rather than seeking advice only after a problem has arisen.
A Humble Disclaimer:
This article is intended for general information and educational purposes only and does not constitute legal advice. Every property transaction has its own facts and circumstances. If we have inadvertently misstated any legal principle or factual matter, we humbly welcome corrections from fellow practitioners, academics and readers.